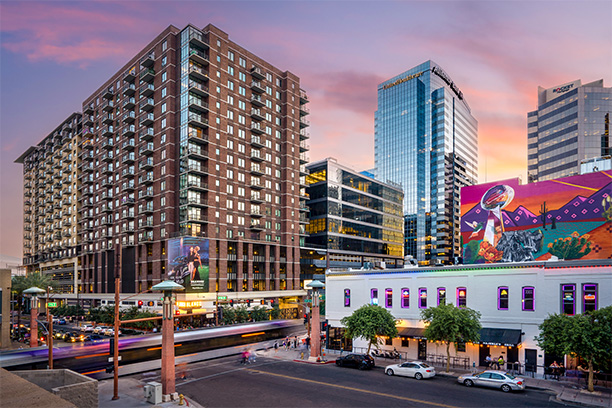
Greater Phoenix’s commercial real estate market is advancing at different speeds. Industrial properties continue to attract substantial tenant demand as new buildings enter the market, while office properties are showing modest signs of stabilization with nearly a quarter of space still vacant. Together, Kidder Mathews’ third-quarter 2026 market reports illustrate how business growth is translating into demand for space unevenly across the Valley.



Industrial leasing reached 7.6 million square feet during the quarter, with direct net absorption of 2.9 million square feet. Direct net absorption measures the change in occupied space, providing a clearer view of market expansion than leasing volume alone, which can include renewals and relocations. Investment in logistics, advanced manufacturing and other industrial sectors continued to support activity as major users expanded their presence.
That demand helped industrial vacancy decline to 11.5%, down 1.8 percentage points from a year earlier. Total availability, a broader measure of space offered to tenants, fell 0.4 percentage points to 14%. The declines indicate that the market has made progress accommodating its growing inventory, even as significant new supply continues to arrive.
Developers delivered 3.4 million square feet of industrial space in the third quarter. That was more than triple the previous quarter’s deliveries but 51% below the same period last year. The different comparisons underscore the importance of looking beyond a single quarter: construction completions accelerated from the spring, while remaining substantially below their year-earlier pace.
Glendale accounted for approximately half of the market’s direct net absorption, recording 1.5 million square feet. Chandler North/Gilbert and the Southwest North of Buckeye Road submarket each contributed roughly one-third of Glendale’s total. Kidder Mathews expects Glendale to remain an important demand driver because of its proximity to TSMC-related supplier and logistics activity.
Building size also matters. Smaller-bay industrial properties continued to benefit from less competition from new big-box space, suggesting that the effects of new construction vary by the type of facility a business needs. Direct average asking rents for industrial spaces of at least 10,000 square feet rose 5% year over year to $1.18 per square foot on a triple-net basis, under which tenants generally pay property taxes, insurance and maintenance in addition to base rent.
The office market’s improvement was more measured. Direct net absorption totaled approximately 23,600 square feet, while leasing activity reached approximately 1.3 million square feet, down from both the previous quarter and a year earlier. Total vacancy stood at 23.7%, declining just 0.1 percentage point from both comparison periods.
Office performance varied considerably by location. The Central Corridor recorded approximately 105,600 square feet of positive net absorption, while East Phoenix posted approximately 64,600 square feet of negative absorption. Those differences suggest that the region’s modest overall gain masks stronger demand in some areas and continued contraction in others.
Building classes showed a similar divide. Class A properties recorded 48,820 square feet of positive direct net absorption and Class C properties added 14,036 square feet. Class B properties posted negative direct net absorption of 39,236 square feet. Sublet space also attracted demand, with Class A sublet absorption totaling approximately 40,300 square feet, just under half of the class’s approximately 89,200 square feet of total net absorption.
Despite those gains, Class A office vacancy remained the highest at 28.3%, compared with 18.5% for Class B and 11.1% for Class C. Average direct office asking rents rose 2% year over year to $31.66 per square foot on a full-service gross basis. Class A asking rents averaged $34.50 per square foot. The rent figures use different lease structures from the industrial report and should not be treated as a direct cost comparison.
Employment provides some support for further improvement. The office report cites 1.3% year-over-year growth in office-using employment in July, the strongest annual increase since mid-2022. The industrial report notes that Arizona added 17,400 jobs between August 2025 and August 2026, although the state’s unemployment rate increased 0.5 percentage point to