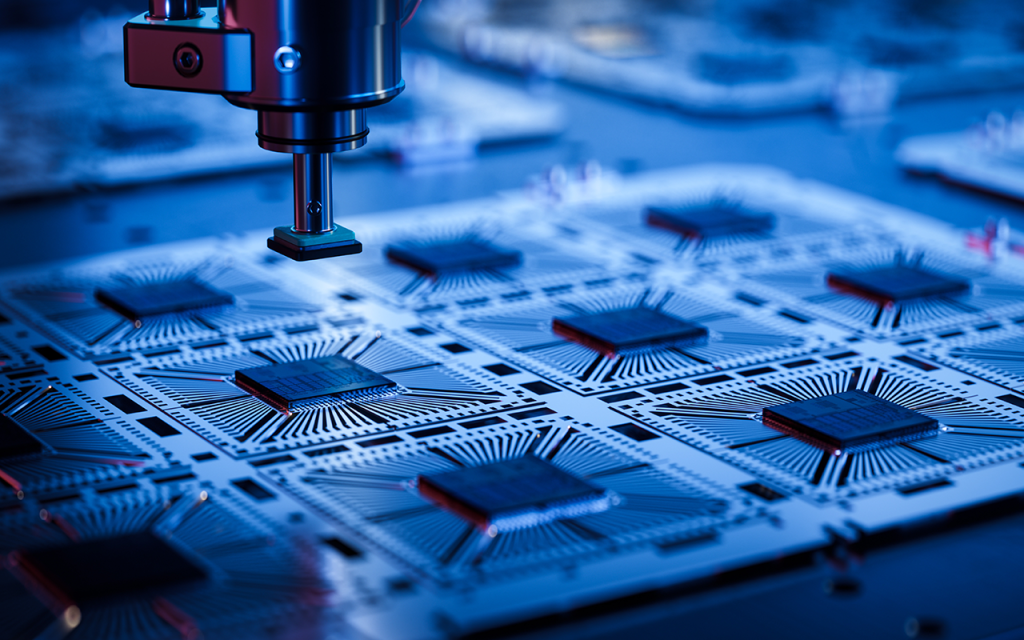
Microchip Technology’s sales are climbing while most of its factory expansion plans remain on hold. The Chandler-based chipmaker reported companywide sales of $1.485 billion for the quarter ended June 30, up 38% from a year earlier. Yet it continued to limit expansion and projected approximately $100 million in capital spending for fiscal 2027.


In north Phoenix, TSMC is preparing for a much larger manufacturing footprint. Its planned Arizona investment has reached $265 billion, with additional factories intended to support demand for advanced chips. Both companies anticipate growth, though their spending plans reflect different stages of turning demand into production.
AI-led expansion and recovery from an earlier downturn are unfolding together in Arizona’s semiconductor economy. One involves committing capital to capacity needed for future orders. The other involves earning more from factories and equipment already in place as customer demand recovers. That distinction helps explain why rising sales, improving profits and new factory spending can move at different speeds.
Building Capacity for Future Demand
TSMC’s spending is concentrated where it expects sustained demand. In July, it raised its global 2026 capital budget to $60 billion–$64 billion, citing customer growth, including AI. Approximately 70%–80% of that budget is allocated to manufacturing technologies for its most advanced chips. The allocation puts the scale of the expansion in context: Investment follows particular technologies and customer requirements, even within a company serving many electronics markets.
Arizona is part of that longer investment horizon. TSMC’s first Phoenix factory began high-volume production in late 2024, while its second is targeting production in the second half of 2027. The company is building a campus whose facilities will begin contributing output at different times. Its multi-year Arizona commitment and its annual global capital budget describe different measures of that expansion.
Construction and equipment installation generate business before a new factory starts shipping chips. Manufacturing revenue follows the ramp into production. The spending cycle therefore reaches different businesses at different stages, with some supplying the buildout and others depending on the volume eventually moving through the finished facilities.
AI-led demand is also creating growth opportunities at Scottsdale-based onsemi. It reported companywide second-quarter revenue growth of 9%, while identifying AI data centers as its fastest-growing business and expecting that business’s revenue to more than double in 2026. Its power and sensing technologies serve automotive and industrial customers as well as data centers. Demand for AI computing creates opportunities beyond the processors themselves, including the chips that manage electrical power.
Onsemi revised its proposed Synaptics acquisition on Oct. 1 to an approximately $5.7-billion cash deal. The California target would add computing and wireless connectivity technology to onsemi’s power and sensing portfolio. Completion is expected by mid-2027, subject to shareholder and remaining regulatory approvals.
Recovering Earnings from Existing Capacity
Microchip’s sales recovery is being supported in part by greater use of existing factories. Management attributed improved profitability to stronger factory utilization, lower costs associated with unused capacity and expense discipline. Its operating margin rose to 22.7% in the June quarter from 3% a year earlier. More activity through existing operations helped the company improve earnings while keeping most factory expansion paused.
The company’s filing also points to a more favorable product mix, lower inventory reserve charges and higher licensing revenue as reasons for improved gross profit. The recovery is rebuilding earnings through several operating changes while factory spending remains restrained. Capital committed in earlier years can support rising sales before the next broad expansion is necessary.
Microchip is still adding equipment selectively for production and research and development. Its results also point to growing activity in data center connectivity. Recovery and investment in newer technologies can coexist, making the company’s restrained factory spending part of a more selective approach to growth.
Expansion and recovery can overlap within a company. A chipmaker may be preparing for rapidly growing AI applications while improving earnings from its existing business. That makes the industry’s investment cycle less uniform than the region’s headline announcements suggest.
Next Street’s September Arizona study, supported by JPMorganChase, reinforces the distinction for the surrounding supplier economy. It finds that supplier investment generally follows demonstrated production demand and facility utilization. Announced factory commitments create potential business, while the pace of manufacturing determines when much of that business materializes.
Arizona’s chip economy is financing new production and earning more from capacity already in place at the same time. The resulting growth extends beyond construction announcements, but its timing and commercial effects vary across the businesses participating in it.